Why Liability Coverage Matters for Galveston Homeowners
When people think about homeowners insurance in Galveston, they often focus on wind, storms, and damage to the house itself. Liability coverage is just as important. This part of a policy is designed to protect a homeowner if someone is injured on the property or if the homeowner, a family member, or sometimes even a pet causes damage to someone else’s property. In a city like Galveston, where homes may host guests year-round, vacation visitors stop by, and outdoor stairs, decks, and pools are common, liability risks are not theoretical. Understanding what this coverage does can help homeowners avoid major out-of-pocket costs after an accident or claim.
How Liability Coverage Works in a Standard Home Policy
Homeowners liability coverage generally helps pay for bodily injury claims, property damage claims, and legal defense costs if the insured is found responsible. For example, if a guest slips on wet steps after a rain shower near the Gulf, liability coverage may help with medical bills, attorney fees, and settlement costs up to the policy limit. This coverage usually applies whether the incident happens at the home or, in some cases, away from the property if the homeowner or a household member causes accidental damage. The key idea is fault. If the homeowner is legally responsible for harm to another person or their property, liability coverage may step in and provide financial protection.
Bodily Injury Claims Are One of the Biggest Risks
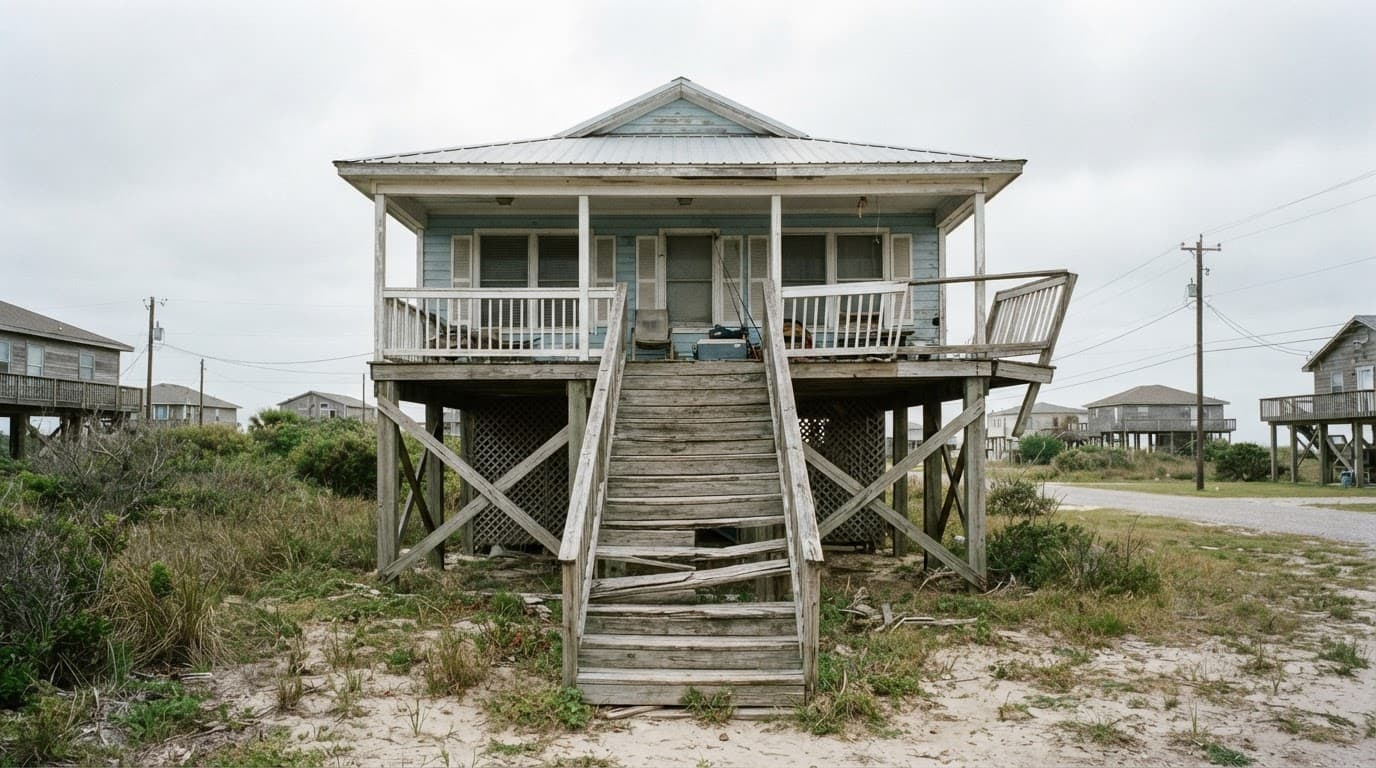
A common liability claim starts with a simple injury. Someone trips on an uneven walkway, falls from a porch with loose railings, or gets hurt around a backyard gathering. In Galveston, elevated homes, exterior staircases, slick surfaces from humidity, and pool areas can all increase the chance of accidents. If a visitor needs emergency treatment, follow-up care, or loses income because of the injury, the costs can escalate quickly. Liability coverage may help pay those expenses when the homeowner is legally liable. It can also help cover the cost of defending a claim, even if the situation is disputed. That legal expense alone can be significant for homeowners who assume minor incidents stay minor.
Property Damage You Cause to Others May Also Be Covered
Liability protection is not limited to injuries. It may also apply when a homeowner, resident family member, or pet causes accidental damage to someone else’s property. A practical example would be a tree from your yard falling onto a neighbor’s fence after poor maintenance is alleged, or a child accidentally breaking expensive equipment while visiting another home in the area. In neighborhoods across Galveston and nearby communities like Texas City, Dickinson, and La Marque, property lines can be tight and disputes can become expensive quickly. Liability coverage can help with repair or replacement costs when the homeowner is legally responsible, which makes it an important layer of protection beyond damage to the insured home itself.
Personal Liability Usually Includes Legal Defense Costs
One part of liability coverage that homeowners sometimes overlook is legal defense. If someone files a lawsuit after an injury or damage claim, the policy may help pay for attorney fees, court costs, and settlements or judgments up to the liability limit. That matters in Galveston because not every claim is straightforward. Questions about maintenance, warning signs, lighting, handrails, pet history, or prior repairs can all become part of a legal dispute. Even when a homeowner believes the claim is exaggerated, responding to it can still be expensive. Liability coverage can provide both money and structure for handling the issue, rather than leaving the homeowner to manage every legal detail alone.
What Liability Coverage Often Does Not Cover
Liability coverage has limits and exclusions, so it is important not to assume it covers every situation. Intentional acts are generally excluded. Business-related claims may also be excluded if the home is being used for activities beyond what the policy allows. Damage to the homeowner’s own property is not handled under personal liability, and auto-related incidents are usually addressed by auto insurance instead. Homeowners in Galveston should also pay attention if they rent out part of the property, host frequent short-term guests, or have features like trampolines, diving boards, or certain dog breeds that can affect underwriting. Those details can change what is covered, what is excluded, or whether higher limits are worth considering.
Why Local Conditions in Galveston Can Affect Liability Exposure
Galveston homes face a different set of day-to-day liability concerns than many inland markets. Salt air and moisture can speed up wear on railings, stairs, gates, and decking. Older homes may have uneven surfaces or aging exterior features that need regular upkeep. Vacation traffic, weekend visitors, and gatherings tied to beach season or local events can increase the number of people coming onto a property. In nearby areas like Kemah, League City, Hitchcock, and Bacliff, homeowners may face similar patterns, but Galveston’s mix of coastal weather and visitor activity makes routine maintenance especially important. Liability claims often start with a condition the owner did not realize had become unsafe, which is why prevention matters as much as policy limits.
Key Takeaways for Choosing a Better Liability Limit
Key Points
- Think beyond the structure of the home. Liability coverage protects against injury claims, property damage claims, and related legal costs when the homeowner is legally responsible.
- Review common risk areas around Galveston properties, including stairs, decks, pools, walkways, pets, and any feature exposed to coastal moisture and wear.
- Check the policy limit carefully. Medical bills and legal defense costs can rise quickly, so many homeowners find that minimum liability limits may not feel adequate.
- Disclose how the property is actually used. Frequent guests, rental activity, or home-based business use can affect whether a standard liability setup is enough.
- Revisit coverage after renovations or lifestyle changes. Adding outdoor entertaining space or other features can increase exposure without changing the house itself.

What to Do Next if You Are Reviewing Your Coverage
If you are reviewing homeowners insurance in Galveston, start by looking at your liability limit, your deductible, and any exclusions or endorsements tied to how the property is used. Then walk the property with a practical eye. Look for loose boards, weak handrails, slick walkways, poor lighting, gate issues, and anything else that could lead to an injury claim. Homeowners in Santa Fe, Pearland, Friendswood, Alvin, and surrounding areas can use the same approach, but coastal properties in Galveston often need more frequent inspection because of weather exposure. Once you know your risks, compare policy options and ask whether higher liability limits or added umbrella protection make sense for your household.