Why Liability Coverage Matters for Galveston Homeowners
Many homeowners focus first on wind, hail, or flood questions, but liability coverage deserves just as much attention in Galveston, TX. Home liability insurance is the part of a homeowners policy that can help pay if someone is injured on your property or if a member of your household accidentally causes damage or injury to someone else. That can include a guest slipping on wet exterior stairs, a dog bite claim, or damage caused by a child riding a bike into a parked car. Because lawsuits and medical costs can rise quickly, choosing the right limit is less about picking the cheapest number and more about protecting what you own.
What Home Liability Insurance Actually Covers
Liability coverage generally pays for bodily injury, property damage, legal defense costs, and certain settlements up to the policy limit. A simple way to think about it is that dwelling coverage protects the house itself, while liability coverage protects the homeowner when a claim is made against them. In a coastal city like Galveston, claims can come from common situations such as guests visiting for beach weekends, delivery drivers walking uneven paths, or contractors and visitors moving around elevated homes with decks and stairs. Policies have exclusions and conditions, so the question is not just whether you have liability coverage, but whether the limit is high enough for a serious claim.
Start With the Standard Limits, Then Pressure-Test Them
Many homeowners policies start with personal liability limits such as $100,000 or $300,000, and some offer $500,000. For many Galveston homeowners, $100,000 can be too low once you consider hospital bills, lost wages, attorney fees, and the possibility of a lawsuit. A broken hip from a fall, for example, can easily create a claim far above basic limits. A practical starting point is to compare your liability limit to your income, savings, home equity, vehicles, and any other assets that could be exposed in a lawsuit. If the answer feels uncomfortable at $100,000, that is a sign to evaluate higher limits before a claim ever happens.
Property Features Can Increase Your Exposure
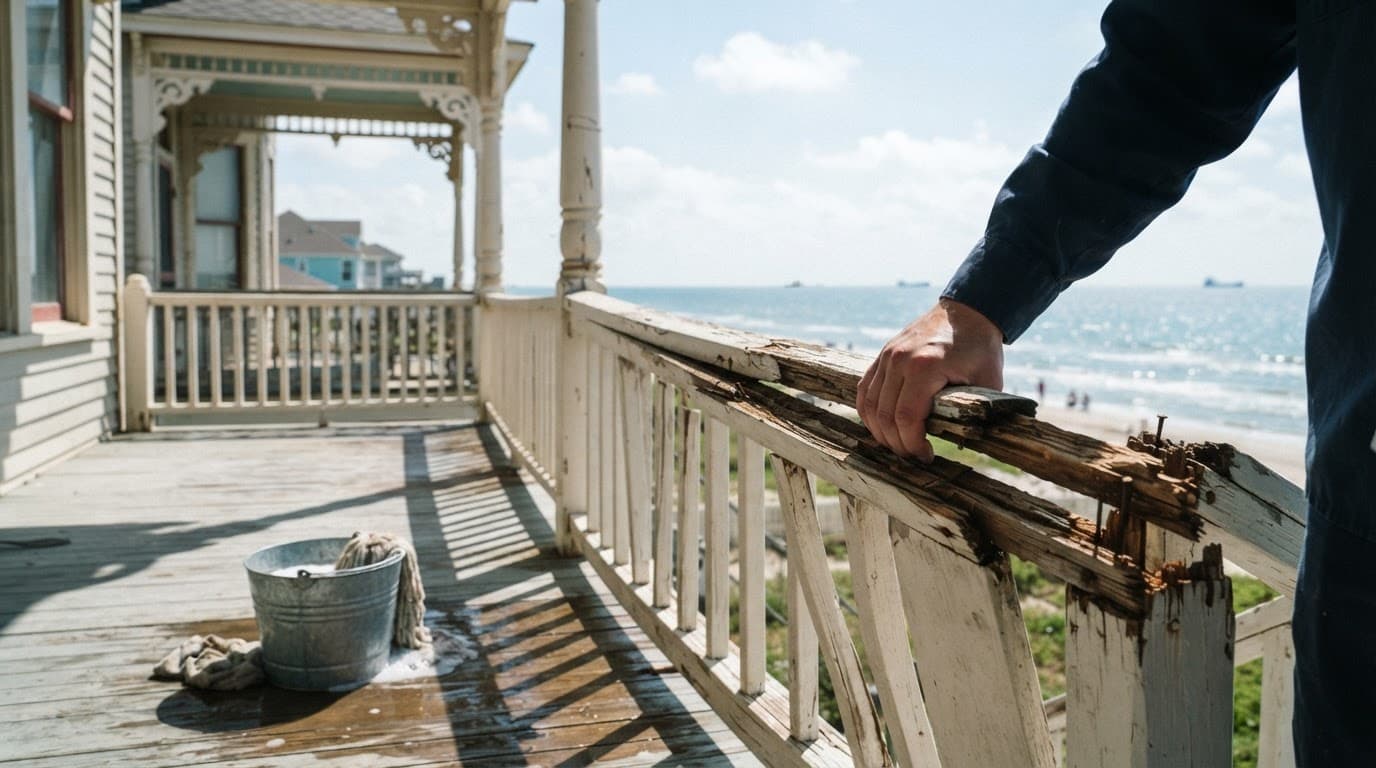
The amount of liability insurance you need often depends on how people use your property. In Galveston, many homes have elevated entries, exterior staircases, patios, pools, docks, or short-term guest traffic from visiting friends and family. Each of those features can raise the chance of an injury claim. Even something as ordinary as poor lighting, cracked concrete, or loose handrails can become a legal issue after an accident. Homeowners in nearby areas like Texas City, Dickinson, and La Marque may face similar concerns, but Galveston properties often have more frequent visitors and more outdoor access points. The more opportunities there are for someone to get hurt, the more important a stronger liability limit becomes.
Your Assets Should Help Determine the Right Limit
A useful rule of thumb is that liability coverage should be large enough to help protect current assets and future earnings from a major claim. If you own a home in Galveston, have retirement savings, keep cash reserves, or own other valuable property, a low limit may leave a gap between your insurance and your financial exposure. This is especially relevant for higher-value homes, second homes, and households with teen drivers, pets, or regular guests. Homeowners in League City, Friendswood, Pearland, and Kemah often review liability through an asset-protection lens, and Galveston residents should do the same. The goal is not to overbuy blindly, but to match coverage with real-world risk.
When an Umbrella Policy Makes Sense
If you need more protection than your homeowners policy offers, personal umbrella insurance may be worth considering. An umbrella policy typically adds an extra layer of liability coverage above your home and auto policies, often in increments starting at $1 million. For Galveston homeowners with substantial assets, a pool, a boat, frequent visitors, rental activity, or multiple vehicles, umbrella coverage can be a practical next step. It is often more cost-effective to add an umbrella than to rely only on base policy limits. The key is making sure the underlying home and auto liability limits meet the umbrella requirements, because umbrella policies usually sit on top of those primary coverages.
Local Risks in Galveston That Affect Liability Decisions
Galveston has a different liability profile than many inland communities. Coastal humidity can make surfaces slick, storms can leave debris or damaged structures, and raised homes often mean more stairs, landings, and railings for guests to navigate. Beach-season gatherings, holiday weekends, and family visits can also increase foot traffic around a property. In neighborhoods near the seawall, bay, or canal areas, there may be added concerns involving docks, water access, or outdoor entertaining spaces. Homeowners in Hitchcock, Santa Fe, Alvin, and Bacliff may see some overlap, but Galveston’s visitor patterns and coastal property layouts make liability review especially important. Local conditions should shape the limit you choose, not just a generic statewide average.
Key Takeaways for Choosing a Liability Limit
Key Points
- A $100,000 liability limit may be too low for many Galveston homeowners once medical bills and legal costs are considered.
- Homes with pools, elevated entries, decks, pets, frequent guests, or water access usually deserve closer review.
- Your coverage limit should reflect assets such as home equity, savings, vehicles, and future earnings, not just the minimum offered.
- A $300,000 or $500,000 homeowners liability limit is often a more realistic starting point for households with moderate exposure.
- Umbrella insurance can add broader protection when base homeowners limits are not enough for the level of risk.

What to Do Before You Choose a Number
Before settling on a liability limit, walk the property as if you were a guest and note any features that could create injury risk. Review whether the household has pets, teen drivers, backyard structures, pools, rental use, or frequent visitors. Then compare that risk profile with the amount of savings, income, and property you would want protected if a claim turned into a lawsuit. For many homeowners in Galveston, the right answer is not the lowest available limit, but a combination of stronger homeowners liability and possibly umbrella coverage. Taking time to compare options, exclusions, and limit choices can lead to a policy that fits real coastal living instead of a one-size-fits-all estimate.